Blog
Impact of Flood Zones on Missouri Property Sales
Real Estate, Missouri Property Law, Flood Zones
How Flood Zones Can Affect a Property Sale in Missouri
Flood risk is more than a line on a map in Missouri it can influence a home’s value, insurance costs, buyer interest, and even whether a sale closes on time. Understanding how flood zones work, and what state rules say about disclosure, helps both buyers and sellers move forward with confidence instead of surprises.
What Is a Flood Zone and Why It Matters in Missouri
A flood zone is an area identified by the Federal Emergency Management Agency (FEMA) as having a particular level of flood risk. On FEMA Flood Insurance Rate Maps (FIRMs), zones such as Zone A or Zone AE typically indicate higher risk, while Zone X often reflects a lower to moderate risk. In a state like Missouri, where rivers such as the Missouri and Mississippi and many smaller waterways regularly impact communities, these zones are a key part of evaluating a property’s true risk profile.
Flood zones can change over time as FEMA updates maps, local development alters drainage patterns, or major flood events prompt new studies. A home that was once outside a high-risk area can be remapped into one, affecting insurance and resale potential almost overnight. Buyers and sellers in Missouri should always check the most recent maps rather than relying on assumptions or outdated information.
How Flood Zones Can Affect a Property Sale
1. Buyer Confidence and Perceived Risk
Many buyers hesitate when they learn a home is in a high-risk flood zone. Even if the property has never flooded, the mere label can raise concerns about safety, future storms, and the potential for costly repairs. This can reduce the pool of interested buyers and lengthen the time a home sits on the market, especially when there are comparable homes outside the flood zone.
2. Insurance Requirements and Monthly Costs
If a Missouri property lies in a Special Flood Hazard Area (often labeled Zone A or AE) and the buyer is using a federally backed mortgage, the lender will typically require flood insurance. These policies are often obtained through the National Flood Insurance Program (NFIP) or private insurers. The cost can be significant and may affect a buyer’s ability to qualify for the loan or feel comfortable with the monthly payment.
Higher premiums can also lead to negotiation pressure. Buyers may ask the seller for a price reduction, closing cost credits, or proof of any mitigation work such as elevating utilities or adding flood vents—that might lower the insurance bill. When these issues surface late in the process, they can delay closing or cause a deal to fall apart entirely.
3. Appraisals, Financing, and Closing Timelines
Appraisers in Missouri consider flood risk when determining value. A home in a high-risk zone may appraise lower than a similar property outside that zone, especially if past flooding is documented. If the appraisal comes in below the contract price, the buyer may need to renegotiate or bring additional cash to closing, either of which can stall the sale.
Lenders may require extra documentation, including elevation certificates, proof of flood insurance, or clarification on prior claims. Gathering these items can add days or weeks to the closing timeline, so sellers who prepare early are generally in a stronger position when negotiations begin.
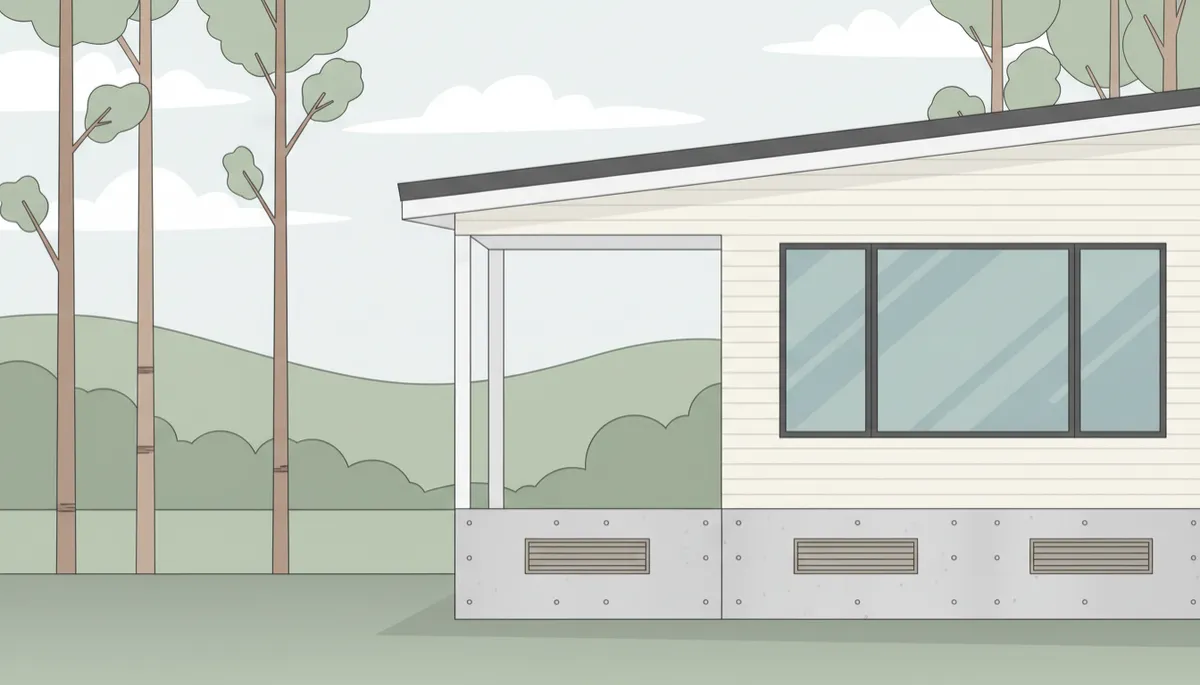
Thoughtful flood mitigation can reassure buyers and support a stronger sale price.
Missouri-Specific Considerations for Flood Zone Properties
Disclosure Duties for Sellers
Missouri law expects sellers to be honest about known material defects, including past flooding or water intrusion. While the exact forms can vary by county or brokerage, sellers are commonly asked to disclose:
Whether the property is in a known floodplain or floodway
Any history of flooding in the house, basement, or yard
Previous flood insurance claims or payouts, if known
Failing to disclose known issues can expose a Missouri seller to legal disputes later. Clear, accurate information up front may feel risky, but it often builds trust and prevents last-minute surprises that derail a sale.
Local Rules, Permits, and Future Improvements
Many Missouri cities and counties participate in the National Flood Insurance Program and enforce local floodplain management regulations. This can affect how a future owner remodels, adds an addition, or rebuilds after damage. Buyers should ask local officials or a qualified professional about elevation requirements, restrictions on building in floodways, and any permits needed for planned improvements.
Practical Tips for Buyers and Sellers in Missouri Flood Zones
For sellers, ordering an elevation certificate, gathering flood insurance records, and documenting mitigation steps (like sump pumps, backflow preventers, or grading improvements) can help answer buyer questions quickly. Pricing the home with flood-related costs in mind can also make the listing more competitive from the start.
For buyers, reviewing FEMA maps, talking with an insurance professional about premiums, and asking specifically about any past flooding are essential steps. A thorough home inspection, including the foundation, drainage, and basement or crawl space, is especially important in Missouri’s flood-prone areas. When both sides approach the transaction with clear information and realistic expectations, flood zones do not have to be deal-breakers—they simply become one more factor in making a smart real estate decision.

John Meier
Westplex Real Estate
504 N State Hwy 47
Warrenton, MO
Phone: (636) 242-5365


