Considerations for As-Is Cash Offers in Real Estate
Real Estate, Home Selling, Cash Offers
What Should You Consider Before Accepting an As-Is Cash Offer?
As-is cash offers promise speed and simplicity, but they also come with trade-offs. Before you sign on the dotted line, it is important to look beyond the headline number and understand what you might be giving up, what risks you are accepting, and whether this path truly serves your financial and personal goals.
Understand What “As-Is” Really Means
An as-is sale means you are agreeing to sell the property in its current condition, with no obligation to make repairs or improvements. The buyer typically accepts the property with all of its visible and hidden issues, from outdated systems to structural concerns. However, that does not mean you can hide known problems. In most areas, you are still legally required to disclose material defects such as water damage, foundation issues, or past insurance claims.
Because the buyer is taking on more risk, they often factor potential repairs into the price they are willing to pay. This is one reason as-is cash offers may come in below what you might expect on the open market after cleaning, staging, and minor updates. The key is recognizing that you are effectively trading some portion of your home’s value for convenience and certainty.
📌 Key Takeaway: You are not paying for repairs, but you are often paying in the form of a lower sale price.
Compare the Offer to Your Home’s Market Value
Before accepting any cash offer, you need a clear picture of what your home could sell for in a more traditional listing. Look at recent sales of similar properties in your neighborhood, ideally those with comparable size, age, and condition. Online estimates can provide a rough starting point, but a local real estate professional or independent appraiser will give you a more accurate view of fair market value.
Once you have that range, compare it to the as-is cash offer and factor in the costs you would incur by selling traditionally: agent commissions, closing costs, holding costs such as mortgage, taxes, insurance, and utilities, plus any repairs or updates a typical buyer might request. In some cases, a lower cash offer may net you a similar amount after you subtract these expenses and the time it would take to sell on the open market.
💡 Pro Tip: Run a simple “net sheet” comparing traditional sale costs vs. the as-is cash number so you are evaluating net proceeds, not just price.
Weigh Speed and Certainty Against Price
One of the biggest advantages of an as-is cash offer is speed. Many cash buyers can close in a matter of days or a few weeks, with minimal paperwork and no lender delays. This can be especially valuable if you are facing a job relocation, divorce, inherited property, or looming foreclosure. The certainty of a quick, guaranteed sale may be worth accepting less than top dollar for your home.
Ask yourself how important timing is in your situation. If you can afford to wait, prepare the property, and navigate showings and negotiations, you might prefer to list with an agent and pursue a higher price. If your priority is to move on quickly with as little hassle as possible, a slightly discounted cash offer could be the right choice. There is no universal answer; it depends on your financial cushion, stress level, and future plans.
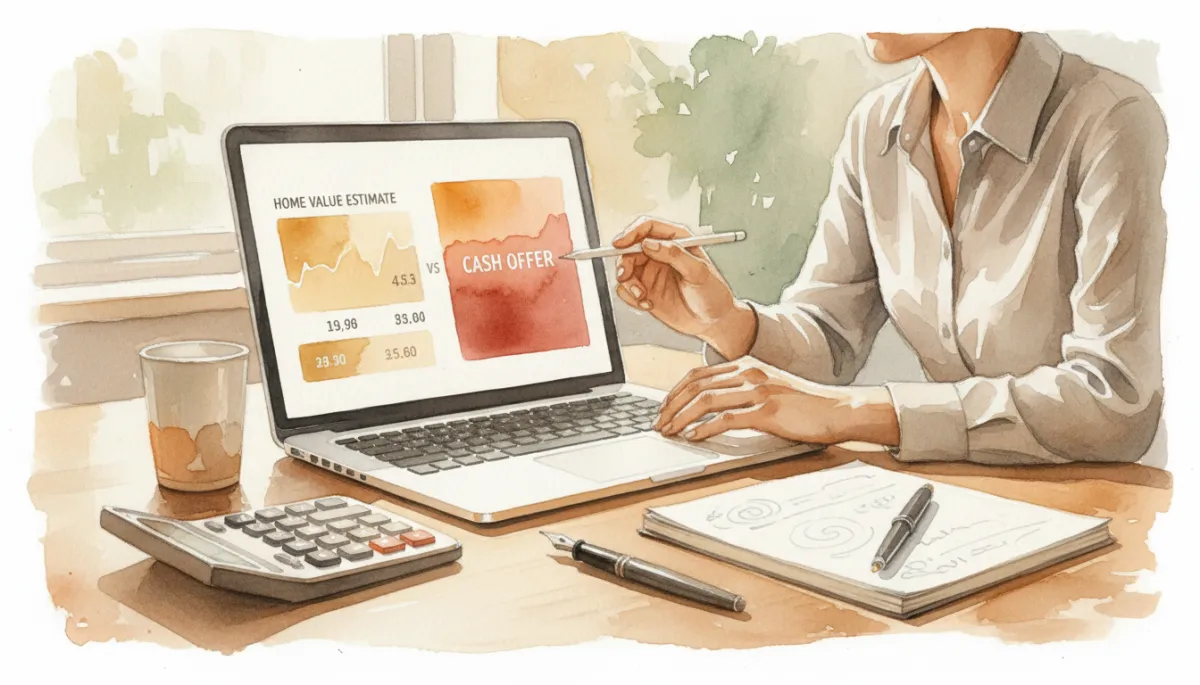
Lining up cash offers with realistic market value reveals the true trade-off.
Review the Buyer’s Terms and Contingencies Carefully
Not all cash offers are created equal. Look closely at the contract terms: Is the buyer truly paying all cash, or is the offer still tied to a hard-money loan or partner approval? Are there inspection, appraisal, or financing contingencies that could allow the buyer to walk away or renegotiate at the last minute? A clean, contingency-free offer is generally stronger and more reliable than one filled with escape clauses, even if the purchase price is slightly lower.
Also pay attention to closing timeline, who pays which closing costs, and whether the buyer is asking for access to the property before closing. If you need time to move, negotiate a rent-back or flexible possession date so you are not scrambling to vacate on short notice. When in doubt, have a real estate attorney or trusted agent review the paperwork to ensure your interests are protected and you fully understand what you are agreeing to.
⚠️ Warning: If the offer is packed with contingencies or early-access requests, make sure you understand exactly how and when the buyer can back out.
Check the Buyer’s Reputation and Proof of Funds
Before you commit, confirm that the buyer is both legitimate and capable of closing. Ask for proof of funds, such as a recent bank statement or letter from a financial institution showing they have the necessary cash available. Be cautious of buyers who refuse to provide this documentation or pressure you to sign quickly without verification.
If the buyer is a company or investor group, search for online reviews, check with the Better Business Bureau, and ask if they can provide references from past sellers. A reputable cash buyer should be transparent about their process and willing to answer your questions. Your goal is to avoid last-minute surprises, cancelled closings, or aggressive tactics that leave you feeling trapped or misled.
Factor In Your Personal Situation and Long-Term Plans
Finally, step back and consider how this decision fits into your broader life and financial picture. Will the proceeds from an as-is cash sale be enough to fund your next home, pay off debts, or support a major life change? Are you emotionally prepared to sell quickly, especially if this is a longtime family home or an inherited property with sentimental value?
There is nothing wrong with choosing the easiest, fastest path if it aligns with your priorities. The key is making that choice with eyes wide open. By understanding what “as-is” truly involves, comparing offers to realistic market value, scrutinizing terms, and weighing your own needs, you can decide whether accepting an as-is cash offer is the right move for you—or whether you are better served exploring other selling options before you commit.
📌 Key Takeaway: The “right” offer is the one that fits your finances, your timeline, and your peace of mind—not just the one with the biggest number on paper.
Ready to Talk Through Your Options?
If you are weighing an as-is cash offer and want a clear, local perspective on what it really means for your bottom line, guidance from an experienced agent can make all the difference.
Contact John Meier – Westplex Real Estate today to start planning your move:
📞 Call or text: (636) 242-5365
🌐 Visit: JohnMeierSells.com
💡 Pro Tip: Even a quick conversation can help you compare your cash offer with other selling paths so you can move forward confidently.


